Retirement After Loss: Moving Forward with Confidence
Losing a spouse changes every part of life, including retirement. As a financial advisor, I often see widows facing not only grief, but also the sudden responsibility of managing finances alone. The emotional weight can feel overwhelming, especially when important financial decisions must still be made.
One of the first things I encourage widows to do is slow down. Avoid making large financial decisions too quickly after a loss whenever possible. It is important to take time to understand what assets exist, what income sources are available, and what expenses may change going forward.
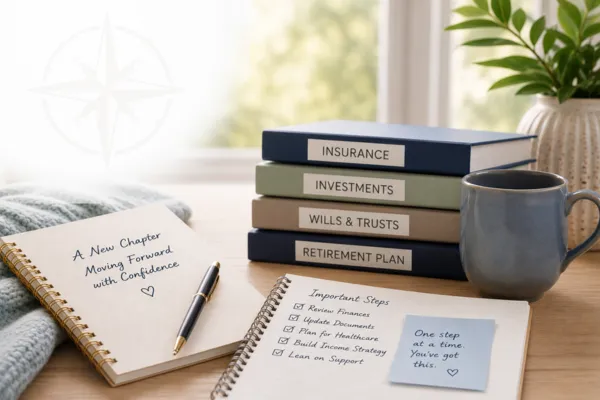
A good first step is organizing the basics:
Gather insurance policies, bank accounts, investment statements, wills, trusts, and tax returns.
Review monthly expenses carefully to understand what retirement income is truly needed.
Update beneficiaries, account ownership, and estate documents if necessary.
Many widows are surprised to learn that their income can change significantly after losing a spouse. According to the Social Security Administration, about 5 million widows currently receive survivor benefits, and many households experience a reduction in monthly income when one Social Security check is lost (Social Security Administration, 2025).
Women also face unique retirement challenges because they generally live longer than men. The Centers for Disease Control and Prevention reports that women in the United States live approximately five years longer on average than men, increasing the likelihood that women will spend more years managing retirement independently (CDC, 2024).
One of the greatest fears widows often express is running out of money. This concern is understandable considering healthcare costs continue to rise. Fidelity’s 2024 Retiree Health Care Cost Estimate found that an average 65-year-old retired couple may need approximately $315,000 saved after taxes to cover healthcare expenses during retirement (Fidelity Investments, 2024).
It is also important to review investments carefully. Studies have shown that emotional stress can impact financial decision-making after a major life event. Research from the Financial Industry Regulatory Authority (FINRA) has found that individuals experiencing major life transitions may become more vulnerable to financial mistakes, fraud, or poor investment decisions during periods of grief and uncertainty (FINRA Investor Education Foundation, 2023).
Another valuable step is simplifying finances wherever possible. Consolidating retirement accounts, automating bill payments, reducing unnecessary debt, and creating a reliable monthly income strategy can help reduce stress and improve confidence.
Healthcare planning becomes especially critical as well. Widows should review Medicare coverage, supplemental insurance, long-term care plans, and emergency savings. Long-term care expenses can significantly affect retirement security, especially for women who often require care later in life due to longer life expectancy.
I also encourage widows not to isolate themselves financially. Ask questions. Meet with trusted professionals. Bring a family member or friend to appointments if needed. Financial confidence does not happen overnight, but it does grow with education and support.
Over the years, I have seen many widows rediscover strength they did not realize they had. Retirement after loss may not look the way they originally imagined, but with thoughtful planning, wise financial decisions, and a strong support system, it can still become a season filled with security, independence, purpose, and hope.
References
Social Security Administration. Survivor Benefits Facts and Figures, 2025.
Social Security AdministrationCenters for Disease Control and Prevention. Life Expectancy in the United States, 2024.
CDCFidelity Investments. 2024 Retiree Health Care Cost Estimate.
Fidelity InvestmentsFINRA Investor Education Foundation. Financial Vulnerability During Major Life Events, 2023.
FINRA Investor Education Foundation
Facebook
LinkedIn
Youtube
Instagram
X