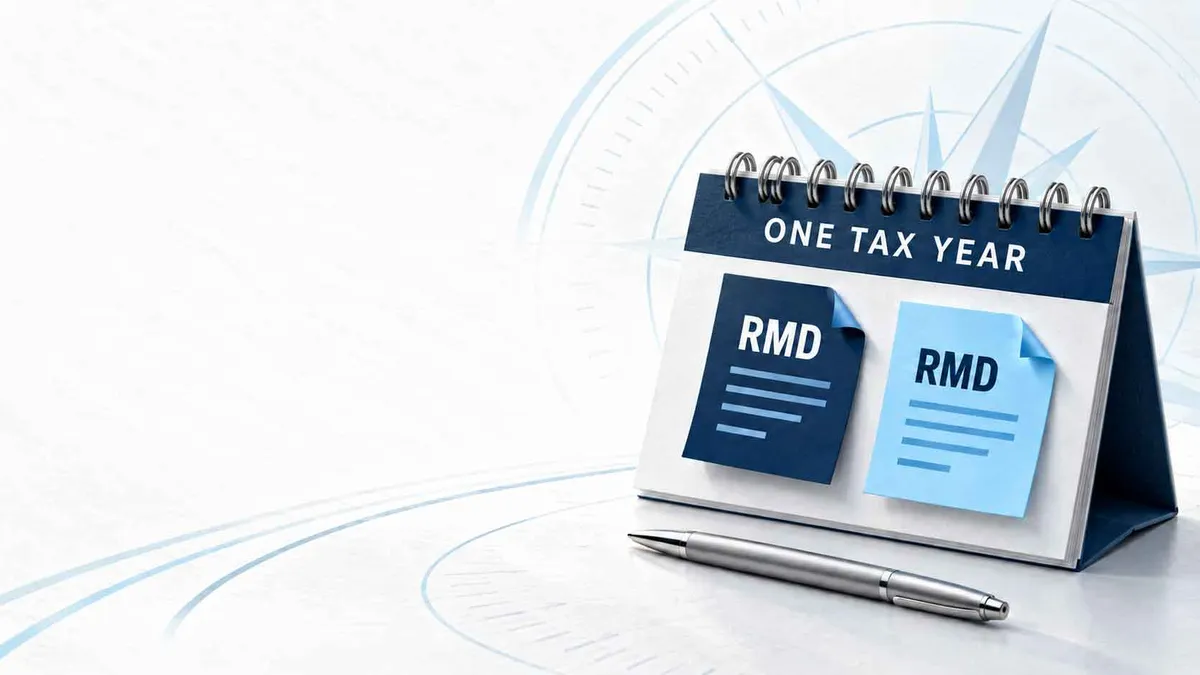
Two RMDs in One Tax Year? What to Know Before Delaying Your First Withdrawal
Waiting to take your first required minimum distribution may give you more time to prepare. But it can also mean taking two required distributions in the same tax year.
In this short video, Jeff Gove explains how that happens and why withdrawal timing matters to your retirement tax plan.
What is an RMD?
A required minimum distribution, or RMD, is the minimum amount you must withdraw annually from certain retirement accounts once the applicable rules require it.
RMDs generally apply to traditional IRAs and tax-deferred workplace accounts, such as traditional 401(k)s. Withdrawals are generally taxable, except for amounts attributable to after-tax contributions.
Roth IRAs and designated Roth workplace accounts do not require distributions during the original owner’s lifetime. Certain employees may also qualify to delay RMDs from their current employer’s plan while still working.
How two RMDs can fall in one year
For someone turning 73 in 2026 whose first RMD is required for that year, the first withdrawal can generally be delayed until April 1, 2027.
However, the 2027 RMD is still due by December 31, 2027.
Taking both during 2027 puts two years’ required distributions into one tax year. Taking the first by December 31, 2026, instead would spread them across separate tax years.
Why timing deserves attention
Combining two RMDs in one year can increase taxable income. Depending on your circumstances, that could mean:
Having some income taxed at a higher marginal rate.
Reducing eligibility for income-based deductions or other tax benefits.
Increasing future Medicare Part B and Part D premiums.
Medicare generally uses income reported on your tax return from two years earlier to determine income-related premium adjustments. The effect may show up later rather than in the year you take the withdrawals.
Compare your options before deciding
Delaying your first RMD is not automatically the wrong choice. The better timing depends on your income, deductions, and broader financial circumstances across both years.
Before choosing a withdrawal date, ask your financial advisor and tax professional to compare the options. Knowing your deadline is the first step; understanding how it fits your retirement plan is the next.
To discuss how retirement withdrawals fit into your overall strategy, contact Stonebridge Wealth Systems.
This information is for educational purposes only and is not individualized tax or legal advice. Consult your tax professional about your circumstances.
Facebook
LinkedIn
Youtube
Instagram
X